
I. THE INTRODUCTION
Special Notices
- Watch the whole conference & support 1776 Law Center. https://www.1776lawcenter.com/2026-conference/v/robert-barnes
A. Art of the Day
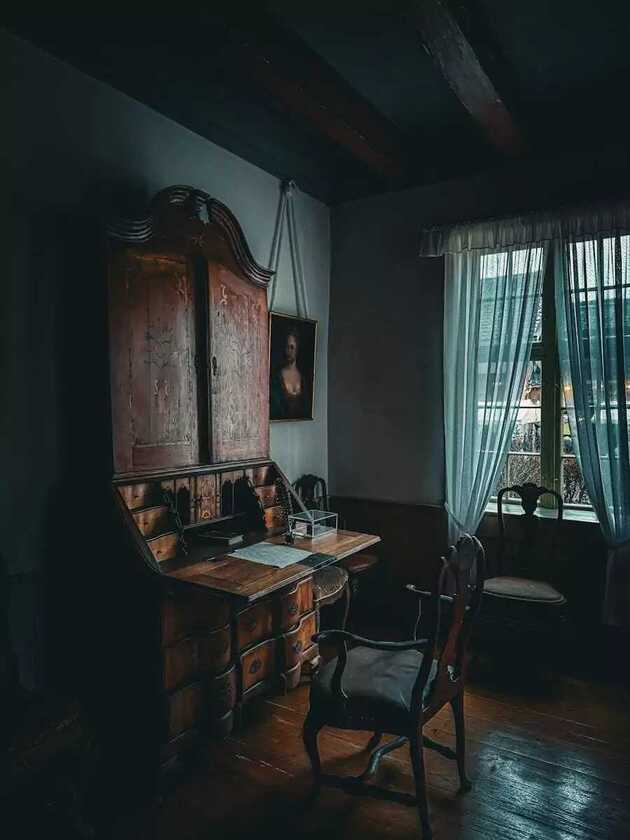
- The old fold-down wooden desk, handcrafted by deliberate care, the little boxes to store letters and notes, the shelf above to carry papers and books, the firm backed, four quared chair with comforting armrests, above the wooden floor and near the open window, the neighboring painting on the wall, that could sit today just as it had centuries ago, taking the work of the mind back to the place our forefathers enjoyed the same.
B. Wisdom of the Day
America is “the champion and vindicator only of her own”, a perfect articulation of America First. John Quincy Adams.
C. Appearances & Publications
- Uploading clips to individual channel. https://www.youtube.com/@robertbarnes5175/videos
- Live w/ Baris
- Live w/ Daniel Davis
- Debate on Mario Nawful
- Live w/ Alex Jones
- LIVE AMA https://sportspicks.locals.com/post/8264800/live-betting-w-barnes-friday-october-16-2026
- Dialogue Works
- Sulaimen
D. Daily Picks
E. *Bonus: Board Post of the Day
II. THE EVIDENCE: BARNES LIBRARY
A. Food & Medicine
- Datacenter health. https://www.midwesterndoctor.com/p/what-is-making-people-near-data-centers
B. Economics
- AI bubble popper? https://quoththeraven.substack.com/p/coreweave-dont-say-i-didnt-warn-you
C. Politics
- Debanking scandal. https://www.thefp.com/p/debanking-investigation-trump-rupa-subramanya
D. Geopolitics
- History of Iran deal. https://larrycjohnson.substack.com/p/why-iran-didnt-walk-away
E. Law
- DOJ challenges illegal votes. https://www.courthousenews.com/wp-content/uploads/2026/10/usa-v-ca-voter-list.pdf
III. HOMEWORK: Ten Top Cases for Sunday Show
- Ex-agents sue Patel. https://www.courthousenews.com/wp-content/uploads/2026/10/fbi-agents-sue-patel-over-mar-a-lao-tied-firings.pdf
- Court allows non-resident voting. https://www.courthousenews.com/wp-content/uploads/2026/10/rnc-v-evnen-opinion-nebraska-supreme-court.pdf
- Social media limits approved. https://www.courthousenews.com/wp-content/uploads/2026/10/netchoice-v-attny-gen-georgia-eleventh-circuit.pdf
- California tries to stop ICE arrests. https://www.courthousenews.com/wp-content/uploads/2026/10/california-vs-ice-complaint.pdf
- Trans bathrooms & federal funds. https://www.courthousenews.com/wp-content/uploads/2026/10/fairfax-county-school-board-v-mcmahon-ruling.pdf
- Court allows sanctuary for illegals in NYC. https://www.courthousenews.com/wp-content/uploads/2026/10/sanctuary-city-dismissed-nyc-eastern-district-new-york.pdf
- Looted paintings. https://www.courthousenews.com/wp-content/uploads/2026/10/norton-simon-vs-jewish-federation-complaint.pdf
- Court demands lottery for immigrants. https://www.courthousenews.com/wp-content/uploads/2026/10/redeagle-v-rubio-ruling-101426.pdf
- California can’t regulate Feds. https://www.courthousenews.com/wp-content/uploads/2026/10/ninth-ciruit-no-vigilantes-act.pdf
- Scotus: Privacy suit. https://www.scotusblog.com/2026/10/court-appears-likely-to-allow-internet-suit-based-on-decades-old-video-privacy-law-to-go-forward/
IV. CLOSING ARGUMENT: Classes in the Constitution, Reminders from our Founding Fathers on Foreign Entanglements
Two founding documents of the founding generation’s approach to foreign entanglments consist of President Washington’s Farewell Address and John Quincy Adams July 4th speech to the House of Representatives in 1821.
Cousin Adams address “on foreign policy” summarized America’s approach to foreign conflicts, by starting with America’s founding rejection of the politics of imperial empire, denouncing Britian’s “portentious system of despotism” with “oppressions of power” governed bby an appetite for “conquest” against the “claims of right” of self-governance. In such an imperial worldview “man had no rights”, where “neither the body nore the soul of the individual was his own” subjecting the people to the “impentarable gloom of this intellectual darkness, and the deep degradation of this servitude” which defined the “British nation” under its imperial mask. These imperial ambitions inflected “the delusions of all Europe” degrading the societies occupied by an intellectually and morally robust people. It was in rejection of these very ideas of empire and presumptions of imperial rule that guided the American revolution.
This animating spirit requires America “respect the indpendence of other nations”, must “abstain from interference in the concerns of others, even when the conflict has been for principes to which America clings.” America “well knows that by enlisting under other banners than her own, she would involve herself beyond the power of extrictation, in all the wars of interest and intrigue, of individual avarice, envy and ambition, which the assume the colors and usrup the standard of freedom” changing her “from liberty to force” creating the hated British “Imperial Diadem, flashing in falkse and tarnished lustre the murky radiance of dominion and power” to become the “distatress of the world” and no longer “the ruler of her own Revolutartionary spirit.”
America is “the champion and vindicator only of her own”, a perfect articulation of America First. That is why America “does not go aborad searching for monsters to destroy.” America’s “glory is not dominion, but liberty.”
Washington warned in his founding Farewell Address: “the nation which indulges towards another an habitual hatred or an habitual fondness is in some degree a slave. It is a slave to it animosity or to its affection.” Washington discouraged any political connections beyond economic trade with nations of the world due to the likely subsuming of a foreign nation’s cause as our own, their antipathies or adversaries as our own, substituting a foreign nation for our own in decision making. Thus the “true policy” of our founders was “to steer clear of permanent alliances with any portion of the foreign world.”
These principles — avoiding the trap of imperial logic, respecting each nation’s own sovereign path, and escaping the entanglements of foreign conflicts — animated the founders. Only when we abandon these precepts and principles do we lose our way. The first promoters of America First were our founders themselves.